Investing can feel intimidating when you are just starting out. The language is full of jargon, the options seem endless, and the fear of making a costly mistake is real. Yet in 2026, opening a brokerage account and beginning to invest has never been more accessible for ordinary people in the United States and the United Kingdom.
This guide is written for beginners and intermediate investors who want clear, practical advice. No hype. No complicated strategies. Just a straightforward explanation of how brokerage accounts work, what to look for, and how to get started with confidence.
Why Investing Matters More Than Ever
Leaving large amounts of cash in a standard bank account means your money slowly loses purchasing power to inflation. Investing gives your money the chance to grow over time through the power of compound returns.
You do not need to be wealthy to begin. Many people start with small regular contributions and build meaningful wealth over years and decades. The key is starting with a solid foundation and avoiding common beginner errors.
What Exactly Is a Brokerage Account?
A brokerage account is simply an account that allows you to buy and sell investments such as stocks, bonds, funds, and other assets. Think of it as a gateway between your everyday bank account and the financial markets.
In the United States these are commonly called brokerage accounts. In the United Kingdom the equivalent is often a General Investment Account (GIA) or a Stocks and Shares ISA, depending on the tax treatment you choose.
The account itself does not make you money. It is the investments you hold inside it that determine your results.
Tax-Advantaged Accounts vs Taxable Accounts
One of the most important decisions you will make is whether to use a tax-advantaged account.
In the United States, popular options include Individual Retirement Accounts (Traditional and Roth IRAs) and workplace plans such as 401(k)s. These offer tax benefits that can significantly improve long-term results.
In the United Kingdom, the Stocks and Shares ISA is the standout option for most people. You can contribute up to the annual allowance and any growth or income inside the ISA is free from capital gains tax and income tax. A General Investment Account has no contribution limits but does not offer the same tax advantages.
Using tax-advantaged accounts first is one of the simplest ways to improve your investing outcomes.
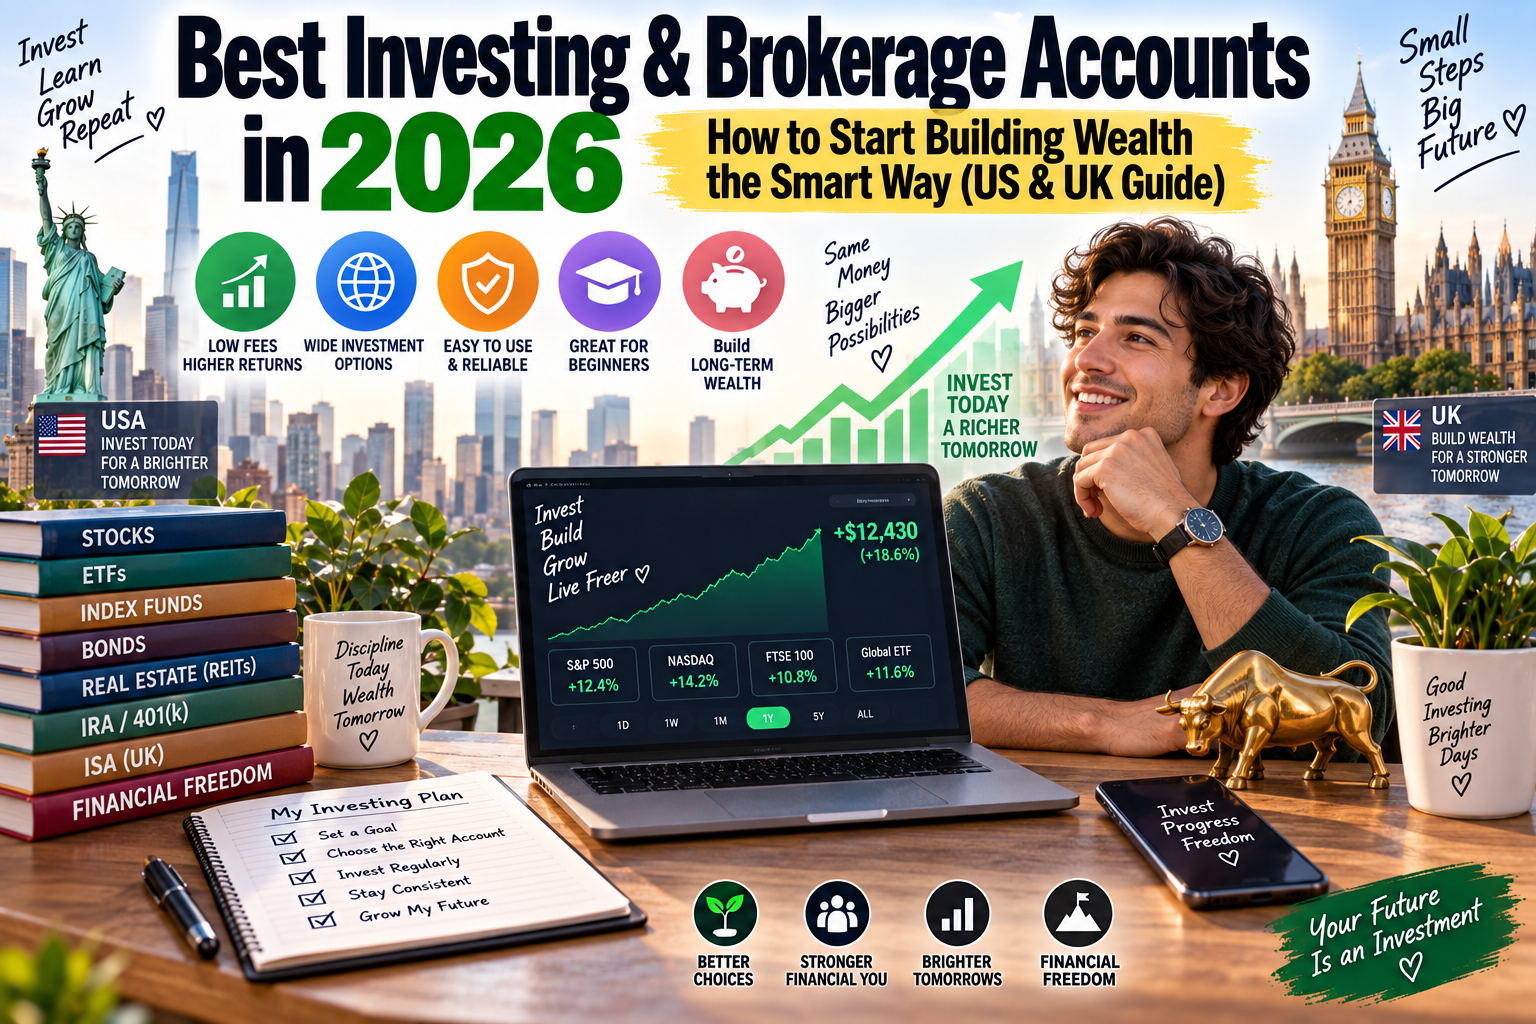
Key Features to Compare When Choosing a Brokerage
Not all platforms are equal. Here are the main factors that matter:
Fees and commissions
Account fees, trading commissions, and fund charges can quietly reduce your returns over time. Look for low or zero commission trading and transparent pricing.
Investment selection
Make sure the platform offers the funds, stocks, or ETFs you are likely to use. Most major platforms now provide excellent access to global markets.
Ease of use
A clean, intuitive interface matters, especially when you are starting out. Mobile apps and educational resources can make a big difference.
Customer service and reliability
When something goes wrong or you have a question, responsive support is valuable. Check recent user feedback on service quality.
Account types and tax wrappers
Confirm that the platform supports the specific account types available in your country (IRAs, ISAs, taxable accounts, etc.).
Minimum deposit requirements
Some platforms allow you to start with very small amounts, while others have higher minimums.
How Beginners Should Approach Investing in 2026
The most reliable approach for most people remains simple and disciplined.
Focus first on low-cost, broadly diversified funds rather than trying to pick individual stocks. Global or total market index funds and ETFs give you exposure to hundreds or thousands of companies in a single purchase. This reduces the risk of any single company or sector damaging your portfolio.
Decide on a regular contribution amount you can sustain. Consistency matters more than timing the market. Many successful investors set up automatic monthly transfers and stick to them through good markets and bad.
Avoid checking your account obsessively. Short-term price movements are normal and often emotionally difficult to watch. Long-term progress is what counts.
Understanding Risk and Time Horizon
All investing involves risk. The value of your investments can fall as well as rise, and you may get back less than you put in.
Your time horizon is one of the most important factors in deciding how much risk to take. Money you need within the next few years generally belongs in safer, more stable places. Money you will not need for ten years or longer can usually tolerate more market fluctuation in exchange for higher expected growth.
Be honest about your ability to stay invested during downturns. The biggest risk for many beginners is not market volatility itself, but selling in a panic when prices drop.
Common Mistakes That Hurt New Investors
Chasing hot tips or recent performance. Past returns do not guarantee future results.
Paying high fees for funds that do not outperform simpler alternatives.
Investing money that will be needed soon.
Failing to use available tax-advantaged accounts.
Checking account values too frequently and making emotional decisions.
Putting too much money into a single stock or sector.
Avoiding these errors puts you ahead of many people who have been investing for years.
Building a Simple, Effective Portfolio
You do not need a complicated portfolio to succeed. Many experienced investors hold just a small number of low-cost funds that cover the global stock market and, if appropriate, some bonds for stability.
As your knowledge and confidence grow, you can refine your approach. In the early years, simplicity is usually an advantage rather than a limitation.
Rebalancing occasionally (bringing your investments back to your target mix) helps maintain your intended level of risk. This can be done once a year or when your allocations drift significantly.
Getting Started: A Practical Sequence
- Decide whether a tax-advantaged account is available and suitable for you.
- Compare a short list of reputable platforms on fees, usability, and account options.
- Open the account and complete any identity verification.
- Set up a regular transfer from your bank account if possible.
- Choose one or two simple, low-cost diversified funds to begin with.
- Invest and then leave the money to work. Resist the urge to tinker constantly.
- Review your overall strategy once or twice a year.
How Much Should You Invest?
There is no single right answer. A common guideline is to invest money you will not need for several years after you have built an emergency fund and paid off high-interest debt.
Starting small is perfectly fine. Many people begin with amounts that feel manageable and increase contributions as their income grows or expenses decrease. The habit of investing regularly is more important than the initial size of the contributions.
Final Thoughts: Time in the Market Beats Timing the Market
Successful investing is less about finding the perfect stock or predicting the next market move and more about consistent behaviour over long periods. Opening a good brokerage account, using tax-advantaged wrappers where available, keeping costs low, and staying invested through market cycles have helped millions of people build wealth.
You do not need to become a financial expert overnight. You simply need to take the first step with a clear plan and avoid the most common pitfalls.
In 2026 the tools available to ordinary investors are better and more affordable than ever. Use them wisely, stay patient, and give your money time to grow.
You now have a practical framework for choosing a brokerage account and beginning to invest with confidence. Take action when you are ready, keep your approach simple, and focus on the long term.