Insurance is one of those things most people know they need but rarely feel excited about buying. Yet the right cover can protect your finances from a single event that would otherwise take years to recover from. The wrong cover, or no cover at all, can leave you exposed at the worst possible moment.
This guide is written for ordinary people in the United States and the United Kingdom who want clear, practical advice on the main types of personal insurance in 2026. No sales pressure. No confusing jargon. Just straightforward information so you can decide what you actually need and avoid paying for what you do not.
Why Insurance Still Matters in 2026
Life has not become less unpredictable. Cars still get damaged, homes still suffer leaks or storms, people still fall ill, and families still lose income when someone dies or cannot work. What has changed is the range of products available and the ease of comparing them online.
The goal is not to buy every policy that exists. The goal is to protect against risks that would seriously damage your finances while avoiding expensive policies that cover things you can afford to handle yourself.
The Four Main Types of Personal Insurance Most People Need to Consider
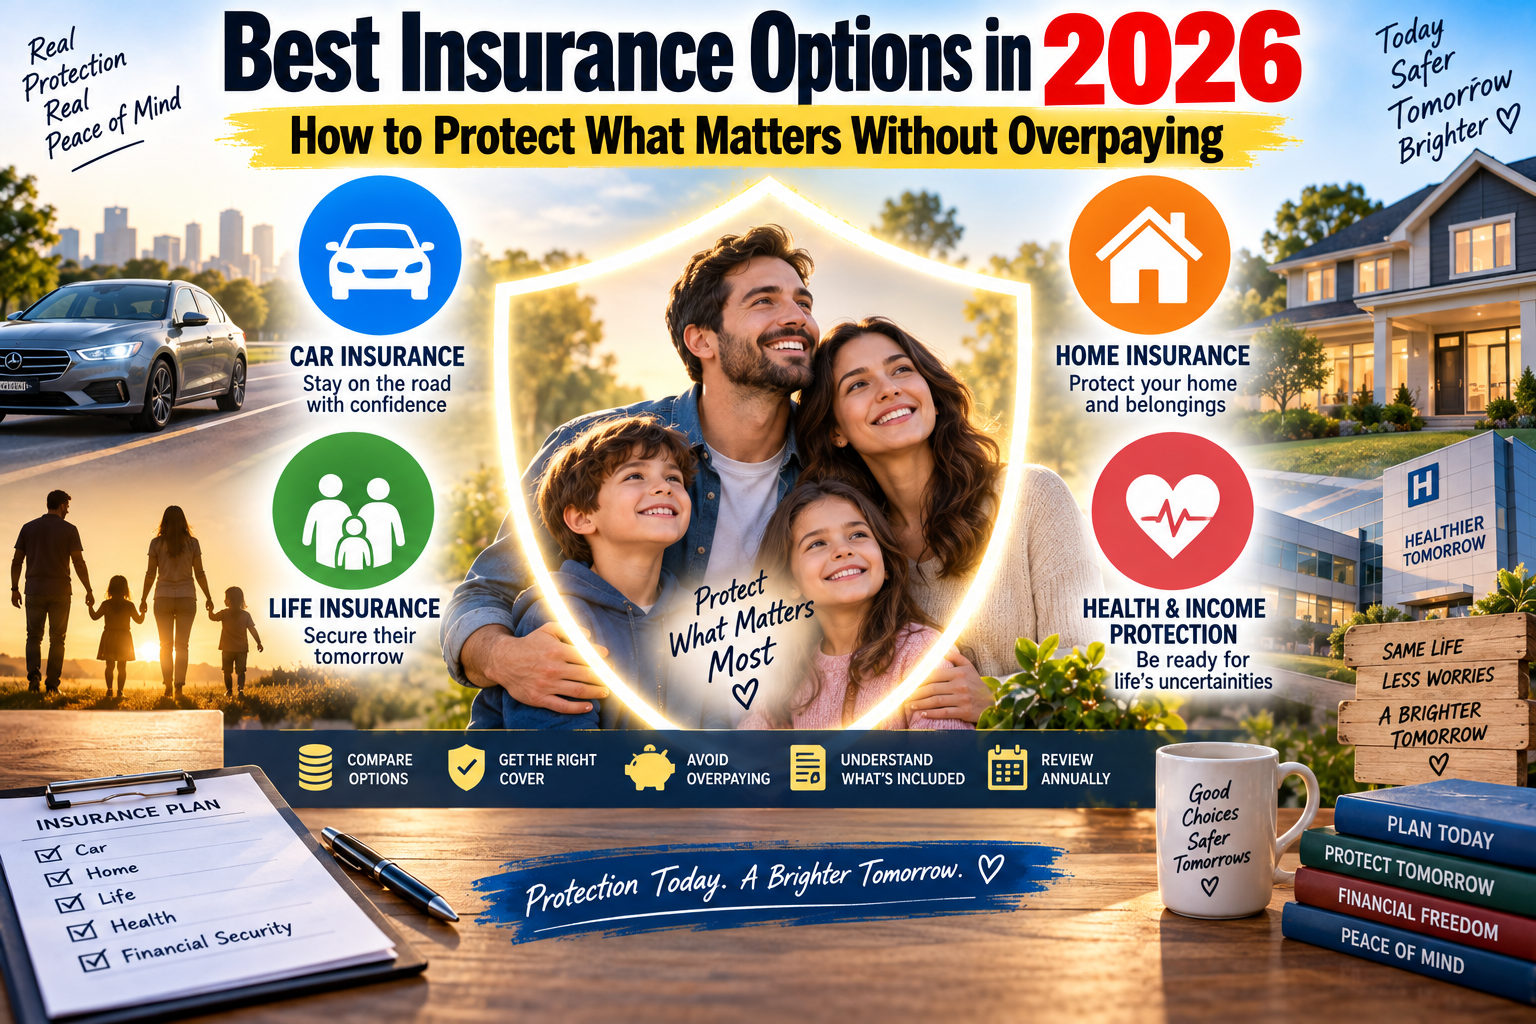
Most households benefit from thinking carefully about these four areas: car insurance, home insurance, life insurance, and health-related cover (including income protection or critical illness in some cases).
Each serves a different purpose. Understanding the difference helps you prioritise.
Car Insurance: Protecting Yourself on the Road
In both the US and UK, car insurance is a legal requirement if you drive. The real question is how much cover you need and how to keep the cost under control.
The basic level protects other people if you cause an accident. Higher levels of cover protect your own vehicle as well. Comprehensive policies usually cost more but can save you significant money if your car is damaged, stolen, or written off.
Your premium is influenced by many factors: your age, driving history, the type of car, where you live, how many miles you drive, and your credit profile in some markets. Small changes, such as increasing your voluntary excess or adding a black box (telematics) device, can sometimes reduce the price noticeably.
Shop around every year. Loyalty rarely pays with car insurance. Many people save by switching providers at renewal time.
Home Insurance: Protecting Your Property and Belongings
Home insurance generally comes in two parts: buildings cover and contents cover.
Buildings insurance protects the structure of the property itself against risks such as fire, flood, storm damage, and certain types of water leaks. Contents insurance covers your belongings inside the home.
If you own your home, most mortgage lenders require buildings insurance. Contents cover is usually optional but strongly recommended. If you rent, you typically only need contents insurance, as the landlord is responsible for the building.
Under-insuring is a common and costly mistake. If you insure your contents for less than their real replacement value, a claim may be reduced proportionally. Take time to estimate what it would actually cost to replace your belongings today, not what you originally paid for them.
Life Insurance: Protecting the People Who Depend on You
Life insurance pays out a lump sum or regular income if you die during the policy term. The main purpose is to protect people who rely on your income — typically a partner, children, or other dependents.
There are two main types. Term life insurance covers you for a set number of years and is usually the most affordable. Whole-of-life or permanent policies last for your entire lifetime but cost significantly more and are less necessary for most families.
The amount of cover you need depends on your outstanding debts (especially a mortgage), the income your family would lose, and any other financial responsibilities. Many people find that covering the mortgage plus several years of income provides meaningful protection without excessive cost.
If no one depends on your income, life insurance is often unnecessary. Buying cover you do not need is one of the easiest ways to waste money.
Health, Income Protection and Critical Illness Cover
In the United States, health insurance remains a major consideration for many households because medical costs can be extremely high. Employer-sponsored plans, marketplace policies, and private options all have different costs, deductibles, and networks. Choosing the right plan involves balancing monthly premiums against potential out-of-pocket costs.
In the United Kingdom, the NHS provides core healthcare, so private medical insurance is optional. Many people choose it for faster access to treatment or greater choice of specialists. Others prefer to self-insure for smaller costs and only consider cover for more serious situations.
Income protection insurance replaces a portion of your income if illness or injury prevents you from working for an extended period. Critical illness cover pays a lump sum if you are diagnosed with a specified serious condition. Both can be valuable, especially if you have limited emergency savings or dependents, but they are not essential for everyone.
How to Decide What You Actually Need
Start with the risks that would cause serious financial damage. A major car accident, a house fire, or the death of a primary earner can be devastating. Smaller risks, such as replacing a mobile phone or minor repairs, are often better handled through savings.
Ask yourself:
- What would happen to my family financially if I died tomorrow?
- Could I repair or replace my car or home contents without going into debt?
- How long could I survive without income if I became too ill to work?
Your answers will point clearly to the cover that matters most.
Practical Ways to Keep Premiums Under Control
Several strategies consistently help people pay less without sacrificing essential protection:
Increase your excess (deductible) if you can afford to pay more in the event of a claim.
Pay annually instead of monthly where possible to avoid instalment charges.
Bundle policies with the same provider only if the discount is genuine and the cover is still competitive.
Maintain a good credit history where it affects pricing.
Review your policies every year and be willing to switch.
Be accurate when providing information — under-declaring can invalidate a claim later.
Common Mistakes That Cost People Money
Buying the cheapest policy without checking what is actually covered.
Assuming you are covered for something when the policy wording excludes it.
Letting policies auto-renew without comparing alternatives.
Over-insuring by paying for high levels of cover on low-value items.
Failing to update insurers when your circumstances change (new car, home improvements, change in mileage, or moving house).
Taking a few extra minutes to read the key exclusions and limits can prevent unpleasant surprises later.
A Simple Process for Reviewing Your Insurance
- List the risks that would seriously damage your finances.
- Check what cover you already have through work, existing policies, or government schemes.
- Identify genuine gaps.
- Compare policies on cover level and total cost, not just price.
- Choose the option that balances protection and affordability.
- Set a calendar reminder to review everything again in twelve months.
Final Thoughts: Protection With Purpose
Good insurance is not about buying the most expensive policies or covering every possible risk. It is about making sure that a single bad event does not undo years of careful financial progress.
In 2026 the tools to compare and buy insurance are better than ever. Use them carefully. Protect the things that matter most, skip the rest, and review your decisions regularly as your life changes.
You now have a clear framework for evaluating car, home, life, and related cover. Take the time to apply it to your own situation, and you will be in a much stronger position to protect both your family and your finances.