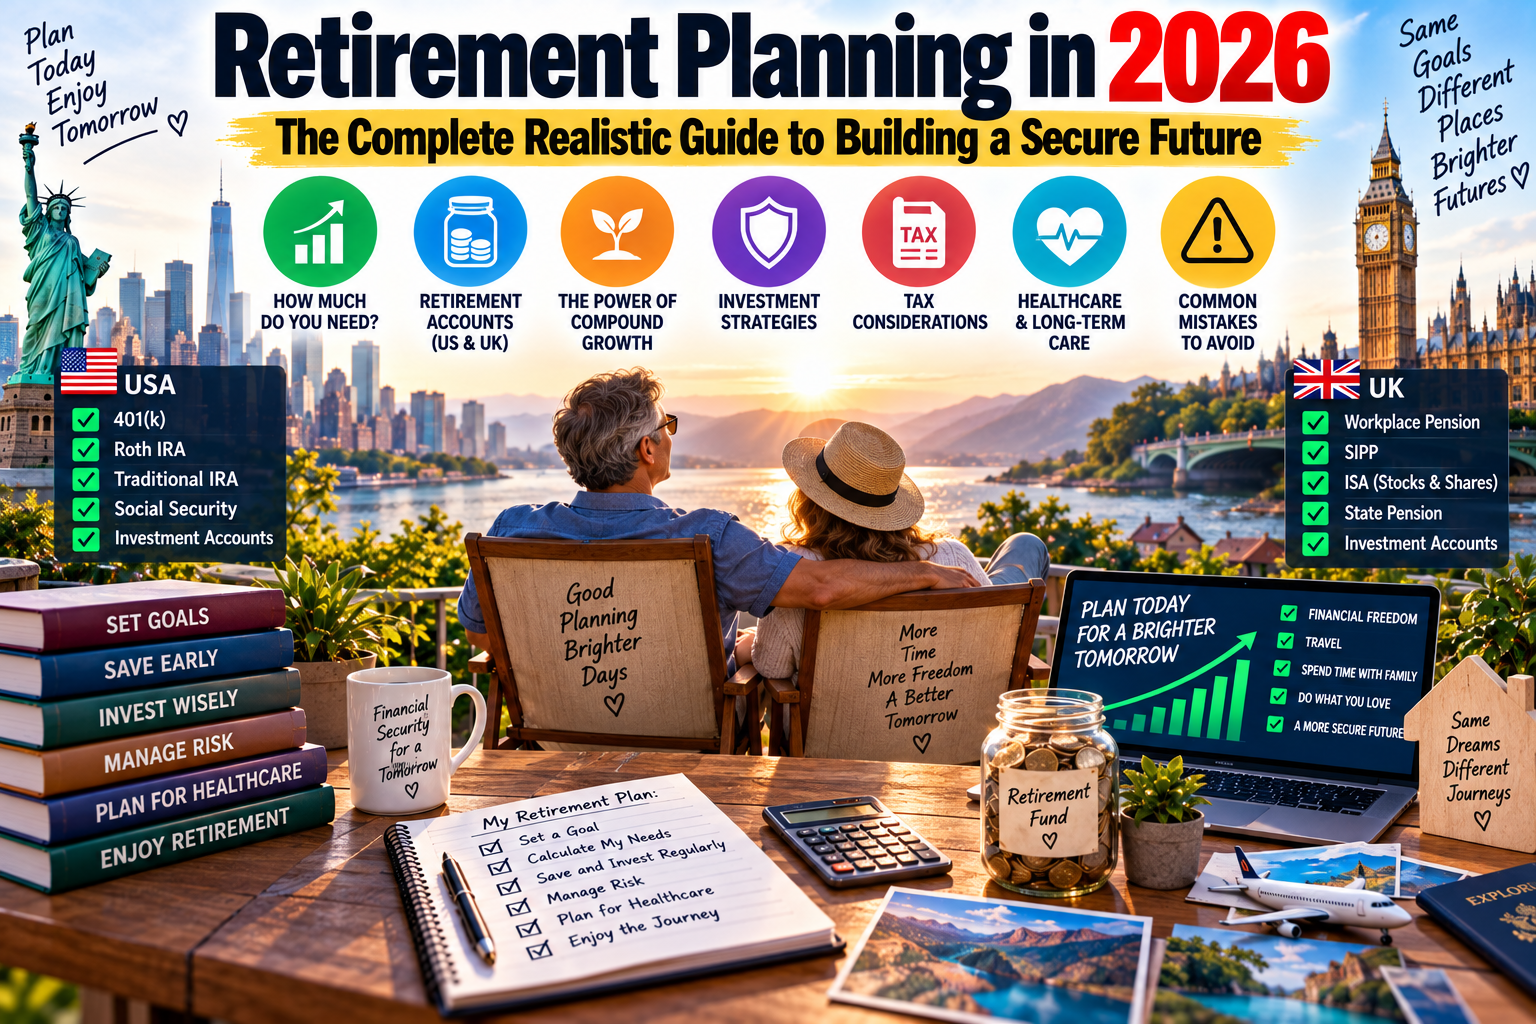
Retirement planning is one of the most important financial tasks most people will ever face. It is also one of the most commonly delayed. Many people intend to start “next year” or “when things settle down,” only to find that years pass and the gap between their current savings and what they will actually need has grown wider. This guide is written for people in the United States and the United Kingdom who want a clear, practical, and honest understanding of how to plan for retirement in 2026. It covers the main account types, how much you may need, the power of starting early, common mistakes, tax considerations, and realistic strategies for both countries. No unrealistic promises. No complicated jargon without explanation. Just straightforward information you can use.
Why Retirement Planning Matters More Than Most People Realise
The length of retirement has increased for many people. Living into your eighties or nineties is now common. That means your savings may need to support you for twenty, twenty-five, or even thirty years after you stop working full-time. At the same time, traditional sources of retirement income have changed. Defined-benefit pensions that paid a guaranteed income for life are less common in the private sector. State pensions and Social Security provide a foundation, but for most people they are not enough on their own to maintain the lifestyle they want.
Inflation quietly reduces the purchasing power of money over time. Healthcare costs in later life can be significant. Unexpected events such as needing long-term care or supporting family members can create additional pressure. Planning ahead gives you more control and more options.
The earlier you begin, the more time compound growth has to work in your favour. Even modest regular contributions can grow into substantial sums over decades. Delaying has the opposite effect: you need to save much more each month later on to reach the same goal.
Understanding the Big Picture: How Much Will You Need?
There is no single correct number. The amount you need depends on the lifestyle you want, where you live, your health, whether you have a partner, and whether you will have other sources of income.
A common rule of thumb is the “replacement ratio.” Many people aim to replace 70 to 80 percent of their pre-retirement income. Someone earning the equivalent of $80,000 or £60,000 per year might target an annual retirement income of $56,000–$64,000 or £42,000–£48,000. This is only a starting point. Some people need less because their expenses fall (no commuting, no work clothes, possibly a paid-off mortgage). Others need more because of travel plans, hobbies, or healthcare.
Another way to think about it is the total nest egg required. Using a conservative withdrawal rate of around 3.5 to 4 percent per year, a $1 million portfolio could support roughly $35,000 to $40,000 of annual income before other sources such as Social Security or the State Pension. These figures are illustrative only. Actual sustainable withdrawal rates depend on market returns, inflation, and how long the money needs to last.
The most useful approach is to estimate your expected annual spending in retirement, subtract guaranteed income sources (State Pension, Social Security, any defined-benefit pension), and then calculate how large a portfolio you need to cover the gap.
The Power of Compound Growth and Starting Early
Compound growth is the process by which your investment returns themselves generate further returns. Over long periods it becomes extremely powerful.
Consider two people. One starts investing $300 or £250 per month at age 25 and continues until age 65. The other waits until age 35 and invests the same monthly amount until 65. Even if both earn the same average annual return, the person who started at 25 will usually end up with a significantly larger pot because their money had ten extra years to compound.
This is why financial advisers repeatedly emphasise starting early. Time is one of the most valuable assets you have in retirement planning. You cannot buy it back later.
Consistency matters as much as the amount. Regular contributions through market ups and downs (often called pound-cost or dollar-cost averaging) reduce the risk of investing a large sum at a market peak and help build the habit of saving.
Retirement Accounts in the United States
The US system relies heavily on individual and employer-sponsored defined-contribution plans.
401(k) and similar workplace plans
Many employers offer a 401(k), 403(b), or similar plan. Contributions are often deducted automatically from your paycheck. Many employers also provide a matching contribution up to a certain percentage of your salary. Capturing the full employer match is one of the highest-return moves available because it is essentially free money.
Traditional 401(k) contributions are usually made with pre-tax money, reducing your taxable income today. Withdrawals in retirement are taxed as ordinary income. Roth 401(k) options, where available, are funded with after-tax money; qualified withdrawals in retirement are tax-free.
Contribution limits are set by the IRS and usually increase over time. People aged 50 and over can make additional catch-up contributions.
Individual Retirement Accounts (IRAs)
If you do not have a workplace plan, or you want to save more, you can open a Traditional or Roth IRA.
Traditional IRAs may allow tax-deductible contributions depending on your income and whether you have a workplace plan. Growth is tax-deferred and withdrawals are taxed.
Roth IRAs are funded with after-tax money. Qualified withdrawals are tax-free. Income limits apply for direct Roth contributions, though backdoor strategies exist for higher earners.
IRAs generally offer a wider range of investment choices than many workplace plans.
Social Security
Social Security provides a foundation of income based on your earnings history. You can claim as early as age 62 with a reduced benefit, or delay until age 70 for a higher monthly amount. The decision involves trade-offs between longevity risk, current cash-flow needs, and other income sources. Many people benefit from delaying if they can afford to do so and expect to live into their eighties or beyond.
Retirement Accounts in the United Kingdom
The UK system combines a State Pension with workplace and personal pensions.
State Pension
The new State Pension provides a regular income if you have sufficient National Insurance qualifying years. The full amount is set by government and usually increases each year. It is a valuable foundation but, for most people, not enough on its own to fund a comfortable retirement.
Workplace pensions
Automatic enrolment means most eligible workers are placed into a workplace pension. Contributions come from you, your employer, and tax relief. The minimum contribution rates are set by law, but many people benefit from contributing more than the minimum.
Defined-contribution workplace pensions build up a pot of money that can be used to provide retirement income. Investment choices and charges vary between schemes.
Personal pensions and SIPPs
Self-Invested Personal Pensions (SIPPs) give you wider investment choice and are popular with people who want more control or who are self-employed. Contributions attract tax relief at your marginal rate (subject to rules and allowances).
ISAs as a retirement supplement
Stocks and Shares ISAs are not pensions, but they are extremely useful for retirement planning. Growth and withdrawals are tax-free, and there is no requirement to buy an annuity or follow pension access rules. Many people use ISAs alongside pensions for flexibility.
Pension access rules
From age 55 (rising to 57), you can usually access defined-contribution pensions. Options include taking a tax-free lump sum (typically 25 percent), buying an annuity for guaranteed income, or using flexi-access drawdown to keep the money invested while taking income as needed. Each option has different tax and risk implications.
How Much Should You Save?
A widely cited guideline is to save 10 to 15 percent of your gross income for retirement across your working life, including any employer contributions. This is only a rough benchmark. If you start later, you may need to save a higher percentage. If you have a generous defined-benefit pension or expect significant other income, you may need less.
The most accurate method is to work backwards from your target retirement income, estimate your guaranteed income sources, calculate the gap, and then determine the savings rate and investment return assumptions needed to close that gap.
Online calculators from reputable sources can help, but treat their outputs as estimates rather than guarantees. Small changes in assumed returns, inflation, or lifespan can produce large differences in the final figures.
Investment Strategy for Retirement Accounts
The investments inside your retirement accounts matter as much as the amounts you contribute.
A common approach is to hold a diversified mix of stocks (for growth) and bonds or other lower-volatility assets (for stability). Younger people with decades until retirement can usually afford a higher allocation to stocks because they have time to recover from market downturns. As retirement approaches, many people gradually reduce stock exposure to lower the risk of a large drop just before or after they stop working.
Target-date funds automatically adjust the mix as you age and are a reasonable default for many people who prefer not to manage the allocation themselves. Low-cost index funds and ETFs are popular choices because they keep fees low and provide broad market exposure.
Fees deserve careful attention. A 1 percent annual fee may sound small, but over decades it can consume a large portion of your returns. Preferring lower-cost options usually improves long-term outcomes.
Common Mistakes That Undermine Retirement Plans
Starting too late is the most costly mistake because it sacrifices years of compounding.
Failing to capture the full employer match in a workplace plan is another frequent error. It is one of the few opportunities for an immediate, risk-free return.
Taking loans or early withdrawals from retirement accounts (where allowed) reduces the capital available for growth and can trigger taxes and penalties.
Investing too conservatively when young, or too aggressively when close to retirement, can both create problems. The first limits growth; the second increases the chance of large losses at a critical time.
Ignoring fees and tax efficiency slowly erodes results.
Assuming Social Security or the State Pension will cover most needs leads many people to under-save.
Failing to increase contributions when income rises means you miss the chance to save more without reducing your current lifestyle as much.
Not reviewing the plan periodically allows it to drift out of line with changing circumstances, goals, or market conditions.
Catch-Up Contributions and Accelerating Progress
Both the US and UK systems allow higher contributions at older ages in recognition that many people need to make up for lost time.
In the US, catch-up contributions to 401(k)s and IRAs are available from age 50. In the UK, the annual allowance rules and carry-forward provisions can allow higher contributions in some circumstances, subject to overall limits and tapered allowances for higher earners.
Even without special provisions, increasing your savings rate by a few percentage points when you receive a pay rise or finish paying off other debts can make a meaningful difference over the remaining years.
The Role of Working Longer
Delaying retirement by even a few years can improve your financial position in several ways. You contribute for longer, the money has more time to grow, and you shorten the period your savings need to support. In the US, delaying Social Security increases the monthly benefit. In the UK, deferring the State Pension also increases the eventual amount.
Working longer is not always possible or desirable due to health or job availability, but where it is feasible it is one of the most powerful levers available.
Healthcare and Longevity Risk
Healthcare costs in retirement are often underestimated, particularly in the United States where Medicare does not cover everything and long-term care can be expensive. In the UK the NHS provides core coverage, but social care costs can still be significant.
Longevity risk is the possibility of living longer than expected and outliving your savings. Planning for a longer lifespan than average, or combining portfolio withdrawals with some guaranteed income (annuities or State Pension/Social Security), can reduce this risk.
Creating a Practical Action Plan
- Estimate your target retirement income and the age at which you hope to retire.
- List all current retirement accounts and their balances.
- Calculate your current savings rate including employer contributions.
- Capture any available employer match immediately.
- Open or maximise contributions to tax-advantaged accounts (401(k), IRA, workplace pension, SIPP, ISA).
- Choose a simple, diversified, low-cost investment approach appropriate for your time horizon.
- Automate contributions so they happen without relying on willpower.
- Increase the savings rate whenever income rises or major expenses end.
- Review the overall plan once a year and adjust as needed.
- Consider professional advice if your situation is complex (multiple pensions, defined-benefit schemes, significant assets, or approaching retirement).
Final Thoughts: Progress Over Perfection
Retirement planning does not require perfection. It requires starting, remaining consistent, and making sensible adjustments over time. The people who reach retirement with adequate resources are rarely those who found a secret strategy. They are usually those who began early enough, contributed regularly, kept costs low, used tax-advantaged accounts, and avoided major behavioural mistakes.
In 2026 the tools available — workplace plans, individual accounts, low-cost funds, and online calculators — make it easier than ever for ordinary people to build a solid foundation. The hardest part is often simply beginning and then continuing through the inevitable market ups and downs.
You now have a comprehensive framework for understanding retirement planning in both the United States and the United Kingdom. Use it to assess where you stand today, decide on the next practical steps, and build momentum. The earlier you act, the more options you will have later.
Your future self will be grateful for the decisions you make now.